Bring the evidence together.
Connect proposals, budgets and supporting records to the findings they support.
SEED ROUND · RAISING NOW
Software and specialist services connecting evidence, review findings and accountable decisions for climate, nature and agriculture programmes.
AI assists the review. People keep decision authority.
TERRA VITA GLOBAL B.V. ROTTERDAM, THE NETHERLANDS
Primary equity. A 24-month plan
to prove institutional adoption.
Good projects begin with the ground truth.
Start with a defined review problem.
Build a continuing institutional relationship.
01 / THE OPPORTUNITY
Conflicting scopes. Unreconciled budgets. Unclear authority. Reviewers need a coherent record before they can make the next decision.
Connect proposals, budgets and supporting records to the findings they support.
Identify what must change, why it matters and who needs to act before the next review.
Maintain findings, responsible owners, decisions and corrections as a programme develops.
AI assists the review. People keep decision authority. We support evidence and preparation. Funding, verification and approval remain with the responsible institutions.
WHY NOW
Since 1 July 2026, new applications to the Green Climate Fund’s Project Preparation Facility must go through its Partner Portal. Applicants still need a concept note and supporting documentation.
Our opportunity is upstream of submission: help programme teams resolve evidence gaps and maintain a usable record through successive reviews.
Source: Green Climate Fund · PPF application process ↗THE PRODUCT IN PRACTICE
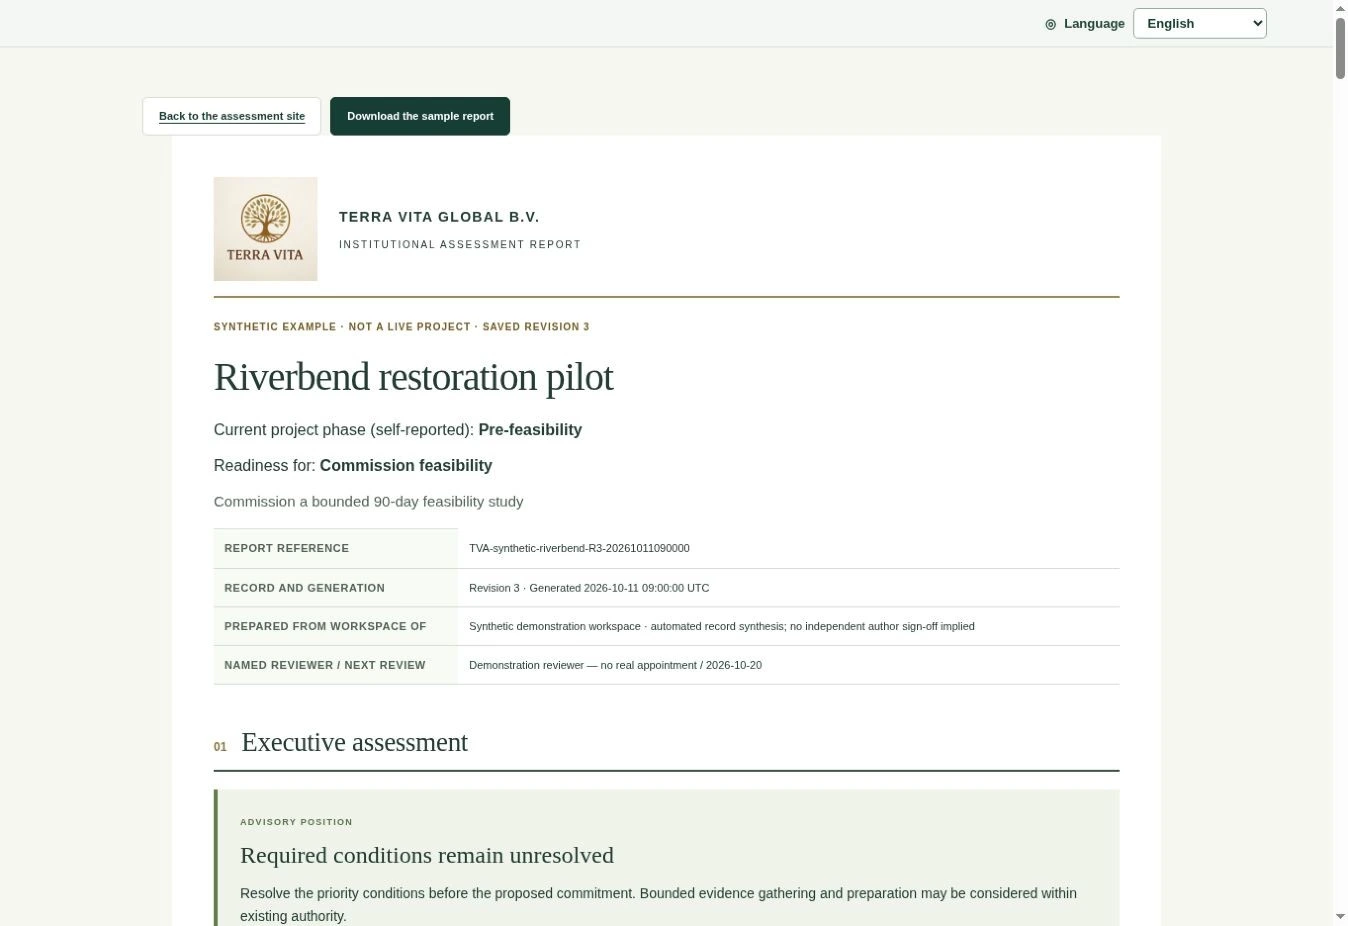
Assessment & Evaluation surfaces evidence gaps and next steps. Terra Vita Hub keeps programme records and review workflows together.
Ready projects can move to Funding Engine Tier 1 when its capital routes match their geography and eligibility.
A REPEATABLE COMMERCIAL PATH
We start with institutions facing a live preparation or review decision. A scoped diagnostic resolves an immediate problem; deployment and continuing access follow when the customer needs an ongoing record.
01 / DIAGNOSTIC
AI assessment, founder evaluation, a findings meeting and revisions, with a readiness report, evidence-gap register, responsibility map and preparation roadmap.
02 / DEPLOYMENT
Configure the workflow and onboard the people who prepare, review and maintain the record.
03 / FUNDING ENGINE TIER 1
Governed capital-route research and read-only Hub readiness and evidence summaries. Invitation authority is outside this tier.
Published prices checked 3 November 2026. Each stage requires a separate purchase, agreed scope and applicable taxes. The €25,000–€45,000 workflow deployment range is an internal planning assumption. The €10,000 institutional diagnostic includes specialist review over 10–15 working days; self-service assessment starts at €49 introductory / €99 standard. Published Tier 1 scope currently covers European capital routes. Eligibility and usefulness for each African programme buyer must be established before purchase; the forecast does not assume automatic conversion from a diagnostic.
EUR list prices, checked 3 November 2026. Of these published offers, only the institutional diagnostic and Funding Engine Tier 1 enter the 2027–2029 core forecast. The separate 2030–2033 outlook proposes a Tier 1–3 customer mix; other offers have no assumed sales volume.
| Offer | Price | Scope / forecast treatment |
|---|---|---|
| Assessment · Single introductory | €49 once | One project assessment; one VitaCore AI review and report exports. Not volume-forecast |
| Assessment · Single standard | €99 once | Standard price; launch end date not published. Not volume-forecast |
| Assessment · Professional | €299 / month | 5 new assessments/month; up to 2 AI reviews per assessment; unused slots expire. Not volume-forecast |
| Assessment · Institutional | By quotation | Quote required for institution-specific assessment access. Quote only |
| Advisory · Clarification round | €540 once | Proposed fee excl. applicable VAT; one project, 3 issues, 5 documents/50 pages, 45-minute call, revised brief; max 3 hours. Not the IAMDES EUR 1,080 scope |
| Diagnostic · Institutional diagnostic | €10,000 once | Agreed scope, contract and invoice before mobilisation. Core forecast |
| Discovery · Explorer | Free | Public catalogue and one private criteria profile. Free |
| Discovery · Professional | €39 / month; €390 / year | Per user; saved opportunities, multiple criteria sets, weekly digest and exports. Not volume-forecast |
| Discovery · Institutional | €2,000 / month | Per institution; mandatory EUR 10,000 diagnostic; governed routing and reviewer controls. Separate offer; not bundled into Tier 1 |
| Offer | Price | Scope / forecast treatment |
|---|---|---|
| Funding Engine · Tier 1 Governed Capital Access | €1,500 / month; €18,000 / year | European capital routes; read-only Hub readiness/evidence summaries; no invitations. Core institutional forecast price |
| Funding Engine · Tier 2 Institutional Actor Access | €2,700 / month; €32,000 / year | Tier 1 plus actor register, governed invitations, route gates and CFR interpretation. 2027–2029 sensitivity; proposed 2030–2033 mix |
| Funding Engine · Tier 3 Full Governance Spine | €4,000–€5,000 / month; €48,000–€60,000 / year | Bounded evidence packs, data rooms and multi-programme routes; signed scope review. Quote range; proposed 2030–2033 mix at €4,000/month |
| Funding Engine · Project | €29 / month; €290 / year | One active project; own-project route mapping, drafting and private evidence. Not volume-forecast |
| Funding Engine · Portfolio | €89 / month; €890 / year | Up to 10 active projects; owner-scoped tools; no institutional access. Not volume-forecast |
| Funding Engine · 30-day Governed Access Window | €4,500 once | Non-recurring read-bounded access; no actor, FieldTrace or invitation authority. Not ARR; not volume-forecast |
| Funding Engine · 60-day Institutional Actor Window | €7,500 once | Non-recurring; 10 verified actor records and route checks; no invitations. Not ARR; not volume-forecast |
| Funding Engine · 90-day Full Governance Window | €12,000 once | Non-recurring; bounded evidence packs and data rooms; no live FieldTrace. Not ARR; not volume-forecast |
| Funding Engine · 90-day invitation add-on | €3,000 once | Separate governed add-on to EUR 12,000 window; total EUR 15,000. Add-on; no double count |
| Offer | Price | Scope / forecast treatment |
|---|---|---|
| Academy · Foundation Deployment | €4,500 once | Up to 10 participants; self-directed digital programme and workbook. Not volume-forecast |
| Academy · Institutional Cohort | €8,500 once | Up to 25 participants; digital programme, workbook, assessment, certificate review route. Not volume-forecast |
| Academy · Cohort + Facilitated Review | €15,000 once | Institutional Cohort plus one 90-minute facilitated review and Q&A. Not volume-forecast |
| Academy · Single Cohort (facilitated) | €12,500 once | Live facilitated delivery for up to 25 participants. Not volume-forecast |
| Academy · Multi-Team Institutional Programme | €28,000 once | Three facilitated cohorts across institutional teams. Not volume-forecast |
| Academy · Donor / DFI Portfolio Deployment | €55,000 once | Up to five programmes or operating environments. Not volume-forecast |
| Academy · Digital Institutional Deployment | €35,000–€75,000 once | Institution-specific digital pathway and custom scenario. Quote range; not generic deployment |
| Academy · Extended Institution-Specific | €75,000–€150,000 once | Expanded configuration, materials and facilitated components. Quote range; not volume-forecast |
| Academy · Funding Spine Reviewer Expansion | By quotation | Specialist reviewer track added to confirmed institutional cohorts. Scoped add-on; no fixed tariff |
Annual prices follow each published offer: Tier 1 €18,000; Tier 2 €32,000; Tier 3 €48,000–€60,000. No blanket annual discount is applied. The €3,000 invitation add-on brings the €12,000 access window to €15,000 total. Access windows are non-recurring. The €540 advisory round is a separate three-hour offer; the IAMDES €1,080 proposal retains its six-hour scope.
THE INITIAL MARKET
Our bottom-up planning estimate uses approximately 3,000 institutions globally and 700 in Sub-Saharan Africa. At €28,000 per institution per year (€18,000 for Funding Engine Tier 1 plus one €10,000 diagnostic), this gives €84 million globally and €19.6 million in Sub-Saharan Africa. Institution counts, annual diagnostic purchases and combined uptake are planning assumptions to validate; deployment fees are excluded.
02 / EARLY PROGRESS
Assessment & Evaluation has seven active project records, excluding demos and samples. Four projects have used Hub since 2026: Somalia, Ukraine, Kenya and Namibia. Funding Engine has seven users and 320 verified capital routes. Routes are research records, rather than investor relationships.
Our assessment product and Hub support evidence review and programme preparation. We are building the institutional offer around the decisions these teams need to make.
Next milestone: three paid institutional diagnostics by Month 6, with accepted outputs and measured delivery effort.The Eldoret project uses Terra Vita Hub for its source-document register, feasibility questions and review records. Proposed €32,400 assignment; scope under revision with the university. The assignment is subject to funded appointment.
Demo available on request Demonstrations use material cleared for sharing.Signed cooperation agreement with AECBED; Hub is the programme’s operating system. It holds programme documents, first-phase evidence acceptance and correction records.
Demo available on request Demonstrations use material cleared for sharing.An assessment for IAMDES turned open questions into a scoped €1,080 clarification proposal. The next commercial step is a commissioned advisory assignment: the assessment-to-service pathway we are building.
Explore the wider programme picture.Product use as of 3 November 2026; Hub records reviewed the same day. Demonstration available in due diligence. Explore the supporting traction dashboard.
WHERE WE FIT
Institutions already use spreadsheets, consultants and grant or monitoring systems. Our focus is the work of connecting source evidence, findings, responsible owners and corrections before and between reviews.
| What teams use today | What it provides | Our focus |
|---|---|---|
| Spreadsheets, documents and specialist consultants | Familiar records, analysis and expert judgement. | Carry the evidence, findings and correction history forward through successive reviews. |
| Submittable ↗ Grant management | Applications, review workflows, awardee communication and reporting. | Prepare and maintain the evidence behind formal applications and review decisions. |
| Field collection and monitoring & evaluation tools | Observations, indicators and programme reporting. | Connect those outputs to the question under review and the person responsible for acting. |
We measure our advantage in the customer’s workflow: less repeated reconciliation, accepted findings, continuing use, and delivery by a second authorised person. Complementary use depends on the agreed scope; no integration or partnership with the named provider is implied.
03 / THE SEED ROUND
We are raising €1m through a priced primary equity round in Terra Vita Global B.V., issuing new ordinary shares. All capital goes into the company. Valuation, ownership and governance terms will be agreed with investors.
Core operating plan from closing.
Raising in November 2026; modelled close: 1 January 2027.
The €500,000 threshold refers to the aggregate first close; individual investment amounts and any later close are agreed separately. On the current model, €500,000 covers the first 12 months of planned spending (€448,000), leaving €52,000 before customer receipts and excluded adjustments. This funds work towards three paid diagnostics by Month 6 and, cumulatively, eight diagnostics, two deployments and two institutional licences by Month 12. These are delivery and sales targets.
With planned Year-1 customer collections of €184,900, modelled cash at Month 12 after a €500,000 first close would be €236,900 before excluded adjustments; this depends on achieving the sales targets and collecting payments on schedule.
If only €500,000 is raised, Months 13–24 commitments would be deferred or reduced unless funded by a later close or collected customer fees. Follow-on funding is not committed. The full 24-month model assumes €1m received on 1 January 2027.
HOW THE CAPITAL IS ALLOCATED
Engineering, delivery and founder commercial capacity.
Specialists, integrations, cloud, software and security.
Legal, accounts, administration and sales travel.
Liquidity before customer receipts. Scheduled work fits the funded delivery capacity.
The €900,000 core budget funds the scheduled workload without delivery top-ups, leaving €100,000 before customer receipts and excluded adjustments. Opening cash balances, outstanding liabilities, tax, VAT, debt and capex are excluded. This is a 24-month operating plan, subject to reconciliation of those items. Programme implementation finance is separate.
WHAT THE ROUND MUST PROVE
Accepted outputs, collected fees and measured delivery effort. Demonstrate Delivery Lead handover.
Eight diagnostics and two deployments in the plan. Test continuing use and operational handover.
Observe renewal and support requirements, and prove a repeatable institutional relationship.
Targets from closing, not achieved results. ARR means annual recurring revenue at the period-end run rate. Model assumption: funding closes on 1 January 2027.
THE FINANCIAL CASE
The first 24 months combine diagnostics, workflow deployments, a proposed Kenya fee and Funding Engine Tier 1 access. The core plan remains €510,900 revenue; forecast sales require new commissions.
Planning: scheduled sales and delivery, with €1m received at closing.
€1,000,000 investment + €505,900 customer collections − €900,000 costs = €605,900 closing model cash. The €5,000 difference between revenue and collections reflects payment timing.
Cash is calculated from customer collections rather than recognised revenue. Opening cash balances, outstanding liabilities, tax, VAT, debt and capex are excluded. The mitigation case assumes achievable spending reductions. These scenarios inform cash planning; they do not establish confirmed company runway.
| Measure | 2027 | 2028 | 2029 |
|---|---|---|---|
| Total revenue | €189,900 | €321,000 | €709,000 |
| Operating expenditure | €448,000 | €452,000 | €630,000 |
| Operating result before tax | −€258,100 | −€131,000 | €79,000 |
| Exit annual recurring revenue | €36,000 | €144,000 | €324,000 |
| Closing institutional licences | 2 | 8 | 18 |
2029 recognised licence revenue is €249,000; €324,000 is the exit annual run rate. The business remains services-led in this core plan. Planning produces a €79,000 operating profit and €684,900 closing model cash in 2029 without further equity, subject to sales, collections and the model’s exclusions.
59 account-months over 24 months; eight active accounts at Month 24 and 18 at the end of 2029. Each row replaces the access price in the same sales schedule.
| Access price basis | Monthly | 24-month revenue | Change | 2029 revenue |
|---|---|---|---|---|
| Funding Engine Tier 1 | €1,500 | €510,900 | — | €709,000 |
| Discovery Institutional | €2,000 | €540,400 | +€29,500 | €792,000 |
| Funding Engine Tier 2 | €2,700 | €581,700 | +€70,800 | €908,200 |
| Funding Engine Tier 3 low | €4,000 | €658,400 | +€147,500 | €1,124,000 |
| Funding Engine Tier 3 high | €5,000 | €717,400 | +€206,500 | €1,290,000 |
These 2027–2029 alternatives are not cumulative sales or an adopted product mix. Higher service scope requires separate demand, delivery and cost validation; the price-only sensitivity does not calculate profit or cash. The separate 2030–2033 outlook below models a proposed tier mix and aggregate costs. Discovery’s diagnostic is not counted twice. Tier 2 uses €2,700 monthly billing here; its separate annual price is €32,000. Academy, self-service and access windows remain outside forecast revenue.
The sales work behind the forecast. €478,500, or 93.7%, of 24-month forecast revenue comes from future sales to customers still to be secured. The remaining €32,400 is the proposed Kenya West assignment. Neither portion is contracted backlog. The proposed assignment’s scope is under revision with the university.
Our 24-month plan requires 18 diagnostics, six deployments, the Kenya West assignment and 59 Funding Engine Tier 1 account-months at €1,500. Founder-led sales starts with a portfolio of 20 priority relationships; the first 18-month activity targets are 40 qualified conversations and 24 scoped proposals, leading to 12 paid diagnostics, with a further 20 qualified conversations and 12 scoped proposals targeted in Months 19–24 to secure the remaining six through continued institutional sales. Both periods use a 30% qualified-conversation-to-paid conversion target and a 50% proposal-to-paid conversion target. These are planning targets, not achieved sales.
The first test is three paid diagnostics by Month 6. If fewer than two of our first ten qualified conversations convert to paid diagnostics within their expected sales cycle, we review targeting, offer and pricing before increasing sales spend.
BEYOND THE CORE PLAN
A separate annual scenario starts from 18 licence accounts and €684,900 model cash in December 2029. These are planning assumptions, not confirmed sales or approved hiring.
| Base scenario · EUR | 2030 | 2031 | 2032 | 2033 |
|---|---|---|---|---|
| Closing active accounts | 28 | 43 | 64 | 93 |
| Total revenue | €881,560 | €1,171,288 | €1,619,837 | €2,293,078 |
| Operating expenditure | €744,000 | €968,000 | €1,204,900 | €1,455,272 |
| Operating result before tax | €137,560 | €203,288 | €414,937 | €837,806 |
| Exit ARR | €551,520 | €926,208 | €1,486,087 | €2,328,678 |
| Closing model cash | €822,460 | €1,025,748 | €1,440,685 | €2,278,491 |
Accounts are expected values rounded for display. Exit ARR measures the closing licence run rate; annual revenue reflects activation timing. No AECBED or similar donor-dependent fees, grants, philanthropic funding or further equity are assumed.
| Proposed base inputs | 2030 | 2031 | 2032 | 2033 |
|---|---|---|---|---|
| New paying licences | 12 | 18 | 25 | 35 |
| Opening-account retention | 90% | 90% | 90% | 90% |
| New customers: Tier 1 | 80% | 70% | 60% | 50% |
| New customers: Tier 2 | 15% | 20% | 25% | 30% |
| New customers: Tier 3 | 5% | 10% | 15% | 20% |
| Average paid capacity (FTE) | 6 | 8 | 10 | 12 |
New accounts contribute six months’ revenue. Existing accounts retain their tier; non-retained accounts bill nothing in that year. Monthly Tier 1 / 2 / 3 prices are €1,500 / €2,700 / €4,000, with no price increases or annual prepayment. Buyer geography, eligibility and scope must fit. No automatic upgrades are assumed.
Services are held at €460,000 a year pending volume assumptions. Cost per FTE is €100,000 in 2030 including employer costs, increasing 3% annually; this replaces the prior people and specialist lines. Non-people costs stay at €144,000 annually. These cost and capacity assumptions require validation as higher-tier use grows.
| Downside scenario · EUR | 2030 | 2031 | 2032 | 2033 |
|---|---|---|---|---|
| Closing active accounts | 21 | 27 | 36 | 48 |
| Total revenue | €570,380 | €682,016 | €868,680 | €1,159,334 |
| Operating expenditure | €744,000 | €865,000 | €992,720 | €1,127,454 |
| Operating result before tax | -€173,620 | -€182,984 | -€124,040 | €31,880 |
| Exit ARR | €405,360 | €559,476 | €801,805 | €1,177,134 |
| Closing model cash | €511,280 | €328,296 | €204,256 | €236,135 |
Downside halves new licences and service revenue, uses 85% retention and 6 / 7 / 8 / 9 FTE. It starts from the same 2029 Planning balance, not the earlier core Downside case, which ends 2029 with €59,000 cash.
Collections equal revenue and costs are paid in-year. The lowest downside year-end cash is €204,256 in 2032, above the €100,000 floor. Intra-year cash troughs and opening cash, liabilities, tax, VAT, debt and capex are excluded. The annual model’s zero additional funding requirement is not an assurance that no further finance will be needed.
Impact evidence: track institutions served, findings accepted by reviewers and programmes reaching verified readiness. Set outcome targets with customers; licence counts alone do not establish climate or nature impact.
THE PEOPLE BEHIND THE WORK
The round funds dedicated engineering and delivery capacity, with practical handover tests and clear operating responsibility.
FOUNDER & CEO
20+ years in programme and project management, including PMO and Dutch-government cleantech work. Built the first working product and leads programme architecture and institutional sales.
Explore Theresa’s profilePART-TIME COO
Delivery coordination, capacity planning and handover support.
ADVISORY CFO
Financial oversight, cash planning and reporting controls.
COUNTRY LEAD EAST AFRICA
Country delivery, programme relationships and institutional sales. Contracted now; employed from funding in the model.
Capacity funded by the roundEngineering lead and a full-time Delivery Lead within two months of funding. Timothy Kiprono is contracted as Country Lead East Africa and moves to employment from close. Role terms and availability require confirmation.
04 / INVESTOR DOCUMENTS
Explore our investment case, commercial assumptions and financial plan in detail.
The 29-slide investment case, revised team and cost plan, pricing and separate 2030–2033 scenario. Public edition.
The full business plan, buyer and programme records, revised costs and a separate 2030–2033 outlook.
The round, traction, commercial model, revised use of funds, team and milestones.
Core annual results, all 36 monthly cash rows, price sensitivities and the 2030–2033 base/downside outlook.
Prefer everything together?
Download the investor packINVESTOR QUESTIONS
A €1m priced primary equity round in Terra Vita Global B.V., issuing new ordinary shares. All capital goes into the company; no founder shares are sold. A first close is possible from €500,000. Valuation, investor ownership and governance terms remain to be agreed.
A 24-month operating plan covering dedicated engineering, a Delivery Lead, Country Lead East Africa, institutional sales and product reliability. The budget comprises €900,000 core expenditure and a €100,000 reserve. Scheduled work fits within funded capacity without delivery top-ups. Programme implementation budgets are separate from Terra Vita revenue.
None of the forecast is contracted backlog. Separately, AECBED has signed a cooperation agreement with fees payable from donor funding; those are excluded from the forecast. Of the €510,900 24-month forecast, €478,500 depends on new sales and €32,400 is the proposed Kenya West assignment, with scope under revision and subject to funded appointment. The first commercial milestone is three paid diagnostics by Month 6.
A live product demonstration, programme-use evidence, the monthly cash plan, IP ownership, team commitments, the cap table and proposed terms. Supporting agreements are available through a confidential review, subject to applicable permissions. The next commercial proof is paid institutional diagnostics followed by separately purchased access where the buyer’s need, geography and eligibility fit.
BUILD THE NEXT CHAPTER WITH US
We invite angels, impact investors, philanthropic investors and family offices with an impact lens to a live product demo and a discussion of the milestones, financial model and seed round.
Founder & CEO · Terra Vita Global B.V.
Start an investor conversation t.vanderwalt@terravita-global.com